

Nigeria’s new tax framework is no longer just a policy conversation; it is about to become an everyday reality.
While Parts 1 and 2 explained the legal structure, the institutions behind the 2026 Fiscal Reform Laws, and the actual reforms, this part focuses on what truly matters to the average person and to business owners: how these reforms affect your income, your transactions, your annual filings, and your financial responsibilities.
In Part 3, we break down:
What the new rules mean for Personal Income Tax – whether you are an employee, freelancer, content creator, or business owner
What has changed for Companies’ Income Tax, deductions, and compliance
Practical steps individuals and businesses can take before 2026
Smart, legal strategies to avoid penalties, audits, interest, and unexpected tax liabilities
The goal is simple: no confusion, no jargon, and no last-minute panic. This is your practical guide to staying compliant and staying ahead under Nigeria’s new tax era.
Understanding Personal Income Tax
Personal tax is the portion of the tax system that applies directly to individuals and their earned income. It determines which types of entries count as taxable income, who is liable to pay tax (often determined by residency or source of income), how taxable income is calculated after allowable deductions and exemptions, and what rates are applied to that taxable base.
For most people, the everyday encounters with personal tax come through payroll withholding (PAYE), taxes on self-employment or side work, taxes on investment returns, and taxes on occasional capital gains. Personal tax systems are designed to be progressive in many countries, meaning that higher earners shoulder a greater percentage of the burden, while exemption thresholds and reliefs protect low earners. The practical effect of personal tax rules is seen in how much of a person’s take-home pay is subject to government collection, how much must be reported annually, and what records an individual must keep to justify claims for allowances and reliefs.
Under the new reform, Nigeria’s personal tax regime has been brought into a single, modern legislative framework that changes both the mechanics of taxation and the practical expectations for taxpayers. The Nigeria Tax Act consolidates previous scattered laws into one act, so what was once governed by different statutes and ambiguous practice is now written into a unified code.
One of the headline changes is the introduction of a reworked, more progressive rate structure and a higher basic exemption for low-income earners; the government explicitly exempted very low earners from personal income tax to protect subsistence-level workers.
The new progressive tax structure is;
0 - 800,000 annually will be taxed at 0%
800,001 - 3,000,000 annually will be taxed at 15%
3,000,001 - 12,000,0000 annually will be taxed at 18%
12,000,001 - 25,000,000 annually will be taxed at 21%
25,000,001 - 50,000,000 annually will be taxed at 23%
Above 50,000,000 annually will be taxed at 25%
Another key change is expanded taxable income. The Act also transfers certain categories of taxable gains, such as capital gains and digital/virtual asset gains, into the personal tax fold, meaning gains that previously had separate, simpler treatment are now assessed under the rules that govern other personal income streams. In practice, that broadening of the tax base means more types of income are reportable, and some gains will be taxed at rates tied to the individual rate schedule rather than at flat, lower CGT rates used previously.
Under the old system, people could avoid tax by claiming their income came from “side hustles,” or “informal trade,” or “cash work.” Not anymore. Under the new tax rule, every inflow is taxable except those that are specifically exempted by law. This means:
If you earn from TikTok, YouTube, affiliate marketing, network marketing, copywriting, data reselling, POS business, bill payment services, or betting commissions, you are now required to register and pay tax.
If you earn from rent, land sales, dividends, or capital gains, those earnings are now taxed under personal tax.
Even digital income and virtual asset gains (like crypto or forex trading) now fall under taxable income in Nigeria.
Most importantly, every individual taxpayer must now have a Tax Identification Number (TIN) linked to BVN, NIN, and bank accounts. Why? Because taxation is moving from voluntary reporting to digital monitoring. Your bank inflows, platform payments, fintech earnings, and transfers can now be legally reviewed by tax authorities.
New administrative features under the reform change how personal taxes are collected and verified. Electronic filing and mandatory digital reporting have been prioritized; the tax administration is being centralized and equipped with stronger powers to cross-check information held by banks and other institutions. This move toward integrated, digital compliance relies on data linkages between taxpayers’ identification numbers, bank verification systems, and other government registries, which makes undeclared income harder to conceal.
For wage earners, employers will face tighter obligations around PAYE reporting and remittance; for freelancers and gig workers, the expectation is clearer record-keeping and registration (for TINs and formal tax returns) even where income is received through electronic platforms. These measures are combined with stiffer enforcement powers for the new revenue body, meaning audits, information requests, and assessments will likely increase as the system becomes more data-driven and centralized.
What this will feel like for ordinary people is not only a change in rates or a slightly different form to fill. It will alter the routine paperwork and choices that determine tax outcomes: whether you declare income from multiple sources, how you report gains from selling assets or crypto, and whether you maintain clear documentation to substantiate deductible expenses or reliefs. The reforms have created clearer rules around exemptions and reliefs (for example, widening certain thresholds and clarifying what counts as non-taxable compensation for loss of employment), but they have also narrowed opportunities to exploit gaps between overlapping laws
For specific taxpayer groups, there are immediate implications. Salary earners must check their employers’ PAYE processes and ensure the right exemption thresholds and rate bands are being applied; small-income earners may find relief through higher exemptions, but those with multiple income streams need to aggregate and report all sources. Self-employed people and freelancers will face a stronger expectation to register and file; income that flows through digital platforms and payment service providers is especially likely to be visible to tax authorities. Also, capital gains from disposals that had simpler or lower tax treatment under the old law may now be treated as part of the personal income schedule, changing both the tax payable and the timing of when tax is due.
What to Expect: Practical Changes From the New Personal Tax Rules
Individuals should expect increased transparency and documentation requirements. The authorities will rely on electronic records and information sharing, so bank receipts, invoices, platform statements, and digital payment records will become the primary evidence of income and gains. There will also be a clearer enforcement path for assessing unreported income because the new revenue service has statutory powers to request data from financial institutions and platform operators. The tax schedule changes mean many low-income earners will be cushioned by exemption thresholds, but middle and higher earners should expect recalculated liabilities under the new progressive bands and potential taxation of previously excluded gains such as certain capital disposals and digital asset profits. In short: fewer informal loopholes, more types of taxable receipts, and more aggressive verification by the tax authority.
What Is Expected from Individuals Under the New Reform?
Mandatory Tax Registration: Every Nigerian with any form of income must register for a TIN.
Annual Tax Filing: Even if you are exempt, you must still file a yearly tax return.
Record Keeping: Individuals must maintain proof of income and expenses.
Separate Personal & Business Income: You must stop mixing bank accounts.
Tax on Multiple Streams: You must declare all income sources, not just salary.
Compliance for Loans & Opportunities: Tax clearance will now be required for loan approval, government grants, contract bids, school scholarships, and visa processing.
The era of “nobody is checking me” is over. The system is moving to digital enforcement. If your account receives money, if you use a fintech platform, if you sell or receive payments online, your activity is visible to the tax net.
How Individuals Should Prepare for the New Tax Reform
Preparation for the new tax system is not something that begins in 2026; it must begin now.
The first step for every individual who earns income in Nigeria, whether through formal employment, freelancing, contract work, online business, or investments, is to become tax visible. This means registering for a Tax Identification Number (TIN) and ensuring it is correctly linked to your BVN and NIN. Without a TIN, an individual will not be able to file returns, verify tax status, or obtain tax clearance, and very soon, a TIN will become a basic requirement for financial processes such as opening a business account, applying for loans, or even entering into certain types of contracts.
Next, every individual must understand that annual tax filing is now compulsory, whether or not tax is actually due. Even if a person earns below the new exemption threshold of ₦800,000 per year and therefore does not have to pay personal income tax, they must still file a Nil Tax Return to formally declare their earnings and claim exemption. The era of staying outside the tax system is over; compliance now starts with filing, not just payment. Filing is what puts a taxpayer in good standing and prevents penalties for non-declaration.
A major mindset shift is also required regarding financial record-keeping. The tax system now demands proof: proof of income, proof of expenses, proof of legitimate deductions, and reliefs. Individuals must retain transaction records, invoices, receipts, transfer evidence, and statements of account.
Whether income is received through banks, fintech platforms, bill payment apps, POS terminals, or online payment gateways, there must be a trail that correctly explains the money received. Casual income that used to be hidden or ignored will now be questioned, and without documentation, such inflows may be classified as taxable income automatically.
Another important area is the separation of personal and business finances. Many small traders, service providers, and side-hustlers operate from one bank account, mixing business transfers with personal expenses. Under the new system, this is a risk. Any individual who earns from business activity, whether small or large, must operate a separate business account or at least maintain traceable records that distinguish earnings from personal inflows. Mixing funds makes it difficult to explain income and increases tax exposure during audits.
Finally, individuals must prepare for the new reality where compliance will determine access to opportunities. Tax clearance is no longer reserved for large business owners; it will soon be required for things that everyday people care about. Loan applications will require proof of tax status. Corporate job roles, government partnerships, talent grants, scholarships, property purchases, and visa applications will begin to request tax clearance certificates as part of due diligence. Even platforms like Paystack, Flutterwave, and other fintech payment providers are gradually integrating tax verification into their onboarding compliance.
In summary, personal taxation under the 2026 reform is not just a legal obligation; it is now part of financial identity. Anyone who earns in Nigeria must now be tax registered, tax documented, and tax compliant. The system has moved from voluntary reporting to digital enforcement, meaning if your account receives money, if you use banking apps, if you run a digital hustle, you are already visible to the tax net. The only question now is whether you will be visible in compliance or in violation.
Understanding Company Income Tax
Business tax refers to the taxes imposed on companies, partnerships, and any other formal business entities for the income they generate. Historically, in Nigeria, business taxes were fragmented across multiple laws and regulatory agencies. Corporate Income Tax (CIT), Value Added Tax (VAT), Withholding Tax (WHT), Stamp Duties, and various local levies were often overlapping, inconsistently enforced, and difficult for small businesses or startups to navigate. For many businesses, especially fintechs, payment aggregators, and high-volume, low-margin enterprises, these complexities made compliance costly, time-consuming, and risky.
The 2026 Fiscal Reform addresses these issues by consolidating and modernizing business taxation under the Nigeria Tax Act, with administrative support from the Nigeria Tax Administration Act and the Nigeria Revenue Service Act. Corporate tax rules are now clearer, digital-first, and designed to capture revenue without creating unnecessary friction for compliant businesses.
One of the most important changes is the requirement for all businesses to register formally with the tax authority and obtain a TIN linked to their corporate bank accounts. This includes fintech companies, bill payment aggregators, and any business that generates electronic transactions, even if profit margins are slim.
A major focus of the reform is digitalization and transparency. Businesses are now required to maintain accurate, auditable records of all transactions, revenues, and expenses. For fintechs and high-volume transaction businesses, this is especially critical. Even if revenue is high, low-profit margins mean that without proper documentation, a business could face misclassification of income, under-deduction of allowable expenses, or penalties for perceived underpayment. The government expects businesses to reconcile daily transactions, merchant inflows, payouts, fees, and commissions, and to generate clear reports that align with tax reporting requirements.
Corporate tax rates have been maintained but are now applied more systematically and transparently. Companies with annual profits below a certain threshold are eligible for reliefs or graduated rates, but all businesses must file returns regularly. VAT compliance has been strengthened; businesses collecting VAT must remit promptly through electronic channels, and the government is paying special attention to digital service transactions. Fintech platforms, e-commerce businesses, online marketplaces, and payment aggregators fall under this category, meaning they must now document every transaction, VAT collected, and service fee earned.
Another key aspect is withholding tax (WHT) and remittance compliance. Payments made to contractors, service providers, or individuals must be reported and withheld as required. Previously, gaps in WHT collection allowed businesses to underreport or delay remittances, but the new law centralizes these obligations and enables direct verification with banks and corporate accounts. Failure to comply can now trigger immediate assessments or penalties.
Finally, the reforms emphasize that tax compliance is directly linked to business growth opportunities. Without proper registration, documentation, and tax clearance, businesses may be excluded from government contracts, grants, financial incentives, and bank financing. For fintechs, this can even affect partnerships with banks or payment networks, as formal compliance is now a precondition for operating in the regulated digital financial ecosystem. In essence, tax compliance is no longer merely a legal requirement; it is a foundational business practice necessary for scaling, accessing funding, and securing operational legitimacy.
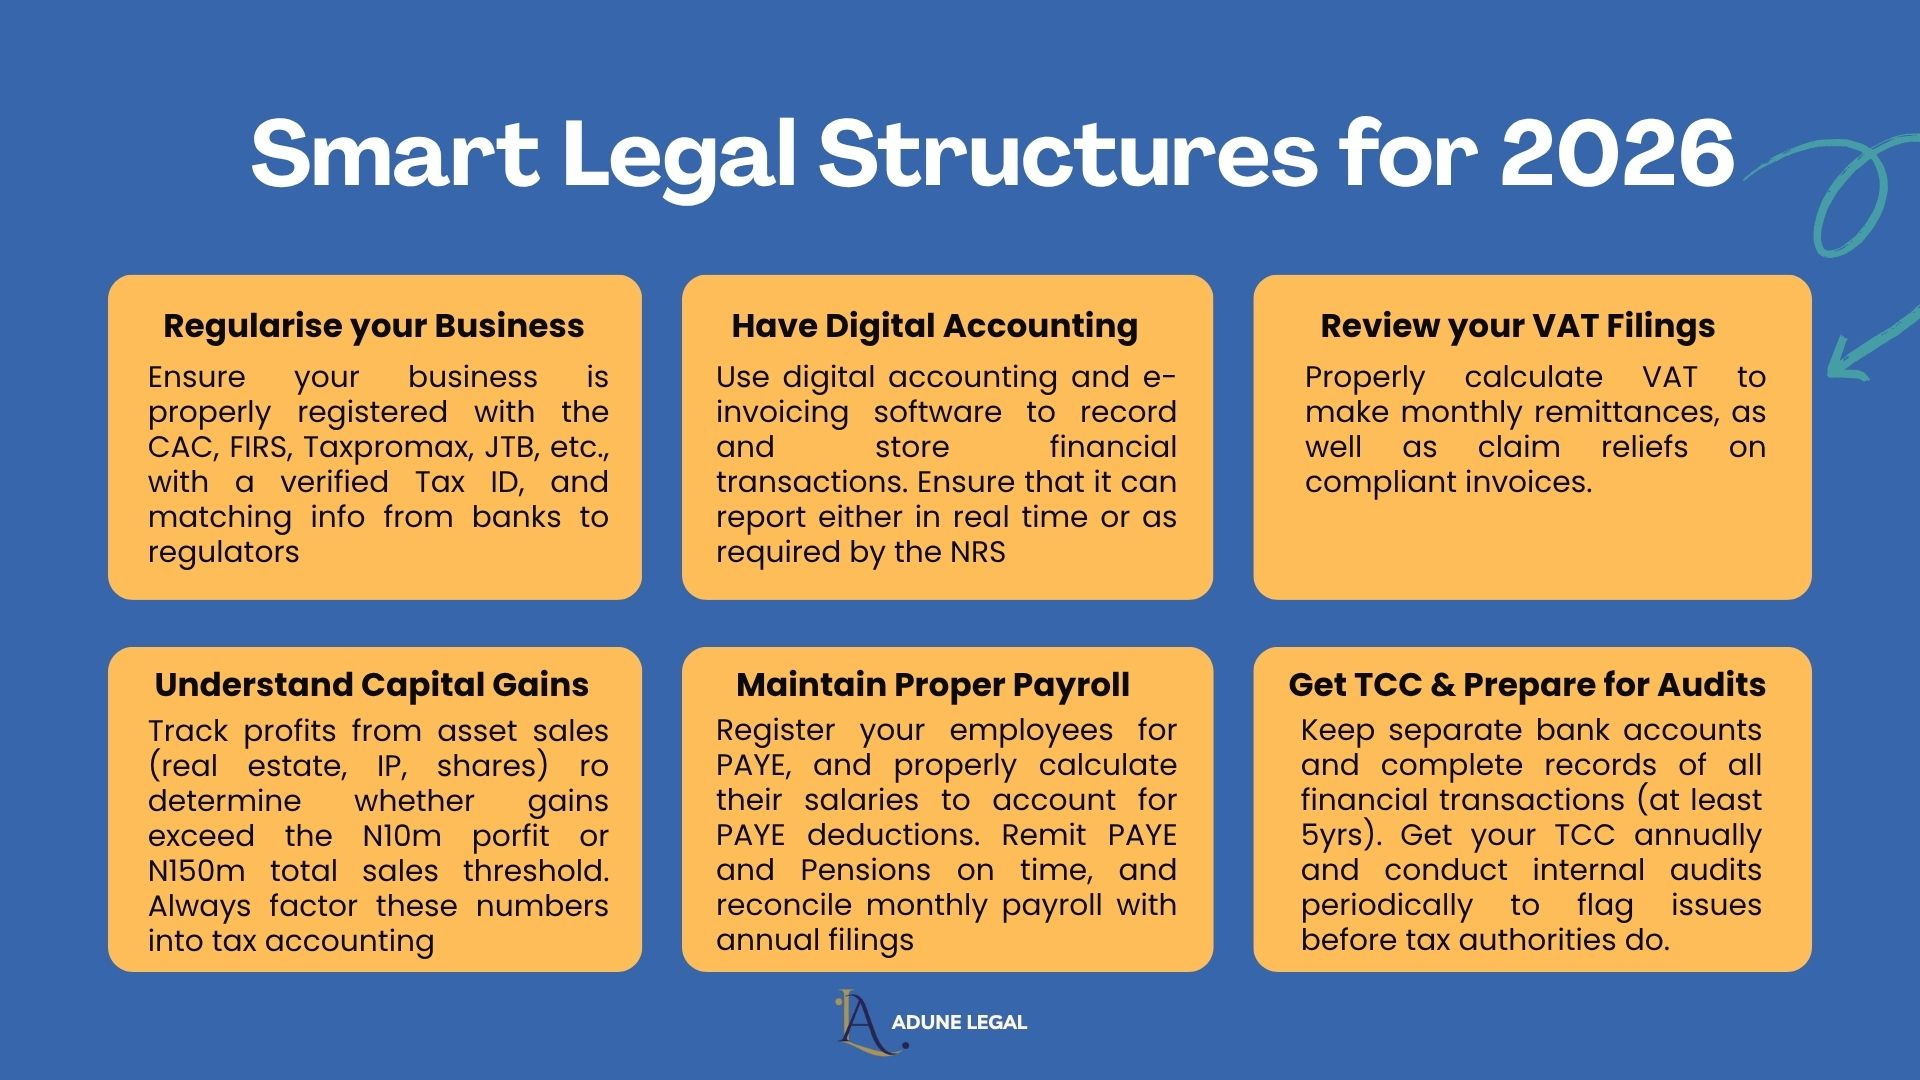
How Businesses Should Prepare for the 2026 Fiscal Reform
Preparation for the 2026 fiscal reform is critical for businesses, particularly fintech companies, payment aggregators, POS operators, and any enterprise handling high transaction volumes but low actual profits. In the past, many of these businesses could operate with minimal formal reporting because individual transaction values were small, and profit margins were slim. But the new reform changes that landscape completely: every inflow is visible, every transaction counts, and every record must be auditable.
Formal Registration and TIN Acquisition
Every business, whether incorporated or operating as a registered sole proprietorship, must obtain a Tax Identification Number (TIN) linked to all corporate bank accounts. For fintechs, this also applies to merchant wallets, agent wallets, POS terminals, and other digital payment platforms. Proper registration ensures that all inflows are traceable and prevents misclassification during cross-checks by the tax authority.
Detailed Record-Keeping
Businesses must maintain accurate records of every transaction, including date, amount, source, destination, and fees charged. Even small transactions count cumulatively. Automated systems are now essential to capture and reconcile payments, commissions, and payouts in real time. Manual tracking is no longer sufficient under the new enforcement regime.
Separating and Categorizing Revenue Streams
Revenue must be properly categorized. For example, a bill payment platform should clearly distinguish between service commissions earned and the funds collected on behalf of clients, because only commissions are considered taxable income. Mixing pass-through funds with revenue increases the risk of over-reporting and misinterpretation by tax authorities.
VAT and Withholding Tax Compliance
Every transaction subject to VAT must be calculated, collected, and remitted on time. Similarly, withholding taxes on payments to contractors, suppliers, or service providers must be properly deducted and remitted. Fintechs with high-volume transactions must implement automated systems to handle VAT and WHT, reducing the risk of penalties and cumulative liabilities that could outweigh actual profits.
Regular Reconciliation and Audit Readiness
Businesses should maintain monthly reconciliations, backup documentation, and clear audit trails. The new system allows authorities to cross-check bank accounts, payment platforms, and TIN-linked records. Proactive review of profitability, expenses, and tax obligations ensures compliance even in low-margin operations.
Adopting Standardized and Digital Processes
Preparation is about visibility, accuracy, and standardization. Businesses should integrate accounting, reporting, and tax software with their payment platforms. This ensures that every inflow, fee, and commission is traceable, categorized correctly, and ready for reporting. Treating compliance as an operational process rather than a legal formality reduces risk and positions the business for growth under the digitized tax regime.
Conclusion
The 2026 reforms are not designed to punish taxpayers — they are designed to organise, formalise, and modernise a system that has been inefficient for decades. Individuals and businesses that prepare early will enjoy smoother operations, fewer compliance risks, and better financial planning. Those who wait until enforcement begins will find themselves spending more time, money, and resources trying to fix avoidable problems.
In Part 4 of this series, we will conclude with a practical guide to the tax reliefs and exemptions embedded in the 2026 reforms, and how your business can leverage them to support compliance and growth.
The future of tax in Nigeria is clear: simple systems, wider compliance, and smarter digital enforcement. The smartest thing anyone can do now is get informed and get ready.
About Legal Bytes
We are Adune Legal’s weekly Newsletter, which simplifies the Law for Busy Executives, Entrepreneurs, and Tech Enthusiasts interested in the legal aspects of Business, Technology, and Intellectual Property.
We love emails from our readers— reply to this email and let us know your thoughts and suggestions.
WAIT!!!
Become a paid subscriber and access;
Q&A sessions with Nneoma Grace via chats on Substack.
Detailed Legal Templates and examples to save you time and legal fees
Expert Interviews and Case Studies
Don’t miss out on these perks - subscribe today and start enjoying it!
Thanks for reading Legal Bytes
Adune Legal’s Team
P.S. Like Legal Bytes? Please forward us to a friend.
P.P.S. Was this publication forwarded to you? Sign up here & see previous publications.